We help businesses accept payments online.
When it comes to accepting payments, almost every Western checkout is heavily skewed towards card payments. That’s because if you’re selling to customers in the West, offering all of the major cards plus a digital wallet like Apple Pay or Google Pay, a BNPL option like Klarna and maybe a local option or two is usually enough to get any customer to checkout.
Japanese customers are different. Where a shopper in New York or London might happily switch from one payment method to another to complete a purchase, a shopper in Tokyo usually won’t.
(If you’re new to the Japanese market, check out our guide to selling into Japan, which goes into detail about Japanese payment methods and why there are so many more than in Europe or the US.)
In fact, studies have found that more than 60% of Japanese shoppers will walk away from a purchase if their chosen payment method isn’t available. For some Japanese customers, they’ll walk away if they can’t pay in cash at their local convenience store (konbini). For others, they’ll abandon their cart if they can’t pay by direct bank transfer. And for 80.1% of Japanese customers aged 15 to 79, they’ll proactively choose to shop in stores where they can collect loyalty points over other shops.
And when it comes to loyalty points, Rakuten is Japan’s biggest and most-popular point ecosystem, with more than 100 million members. In total, almost 60% of Japanese consumers use Rakuten Points, which is significantly more than other programmes like Ponta (41% of Japanese consumers) and d Point (39% of Japanese consumers).
In other words, offering Rakuten Pay at your checkout means that Japanese shoppers are more likely to complete their purchase and keep coming back to keep earning points.
That’s why we’ve put everything you need to know about Rakuten Pay and how KOMOJU can help you add it to your checkout together in one place. This article will cover:
- what Rakuten Pay is
- why Rakuten Points pull so much weight with Japanese shoppers
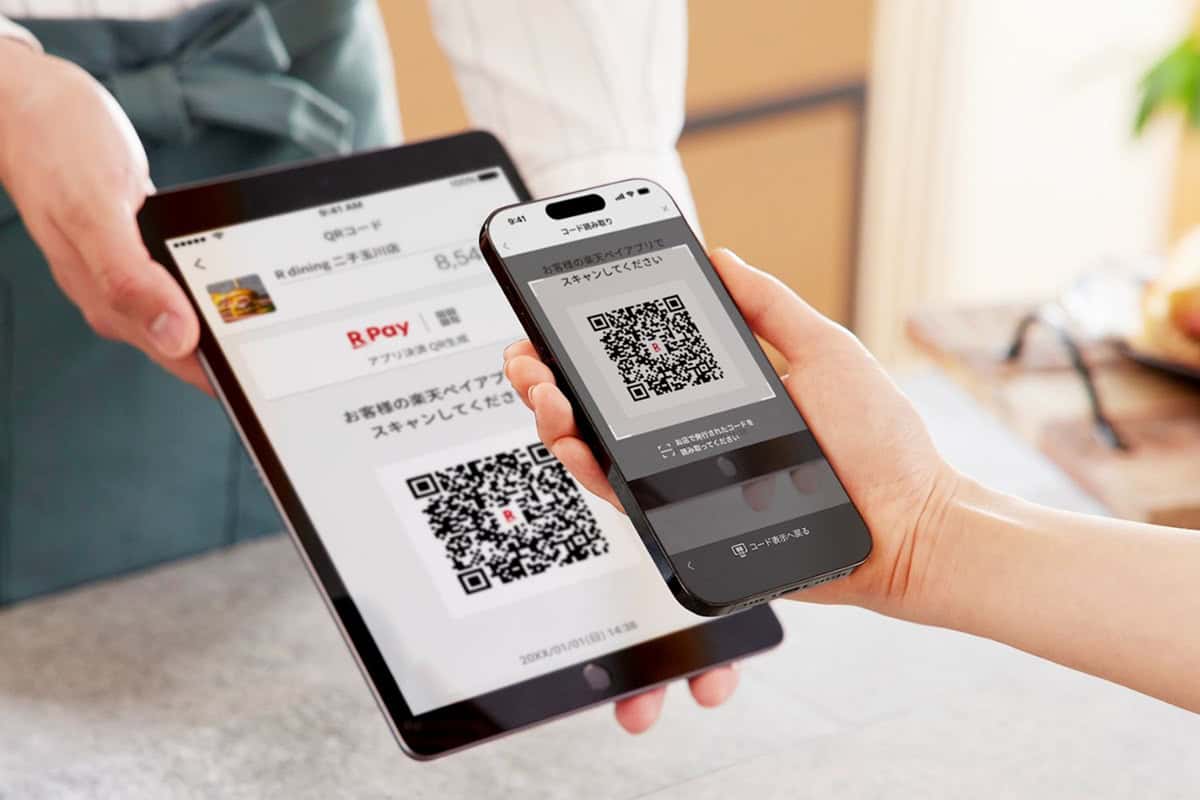
- what paying with Rakuten Pay looks like from your customer’s side
- what it can do for a brand Japanese shoppers don’t know yet
- which payment methods to add first, and where Rakuten Pay comes in
- the local entity question, and how to start selling while you sort it
- fees, payouts, and refunds
- how to run it alongside Stripe or Shopify Payments with KOMOJU
What is Rakuten Pay?
Rakuten Pay is a Japanese digital wallet that was launched in 2016 by Rakuten Group, the company behind Rakuten Ichiba, one of Japan’s largest online marketplaces.
In fact, Rakuten Pay is one of the many services that the Rakuten Group offers alongside Rakuten Card, Rakuten Bank, Rakuten Mobile, and Rakuten Travel. That means that for a lot of people in Japan, Rakuten is a part of daily life. They use it to bank, travel, pay phone bills, and shop both online and in person.
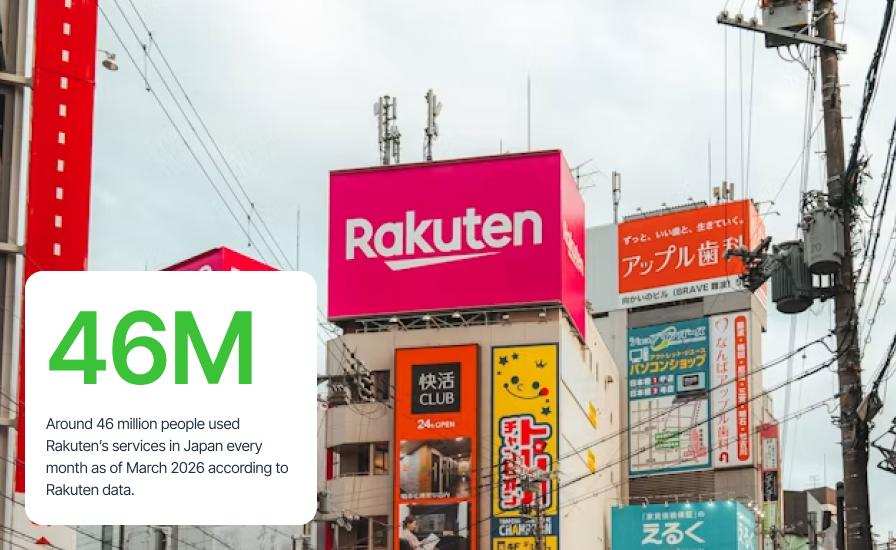
In Japan, consumers use it to pay for goods and services online with their Rakuten ID rather than entering their card details at checkout. Every month, around 46 million people use Rakuten services to pay for goods and services or collect points.
Rakuten Pay gives Japanese customers the choice to use a card that’s saved to their account, pay using their Rakuten Pay Balance (pre-topped up credit) or pay using the points they’ve collected.
(Note for merchants: if a customer pays using their points balance, you still receive the full cash value of the transaction. Rakuten Pay handles that behind the scenes.)
If you offer customers a payment option like PayPal or Amazon Pay, it’s a similar experience where the customer logs in to their account and the payment goes through without them needing to share card details directly with the store.
If you’re looking into adding Rakuten Pay to your checkout, you’ll come across a few related terms:
- Rakuten Pay: the digital wallet that customers use to pay.
- Rakuten Points: these are the reward points customers earn and spend across Rakuten’s services.
- Rakuten Pay Balance: online cash that customers top up inside the wallet, for example from a bank account or with gift cards. (Until May 2026, this was known as Rakuten Cash, so you might have heard that name instead.)
- Rakuten Card: Rakuten’s own credit card, which many customers link to their Rakuten ID.
- Rakuten e-NAVI: Rakuten’s online account area where Rakuten Card holders check statements, manage their card, and resolve any account questions or issues they may have.
- Rakuten Edy: a prepaid e-money card that customers tap to pay, although this is mostly for physical shops
Why do so many Japanese shoppers use Rakuten Pay?
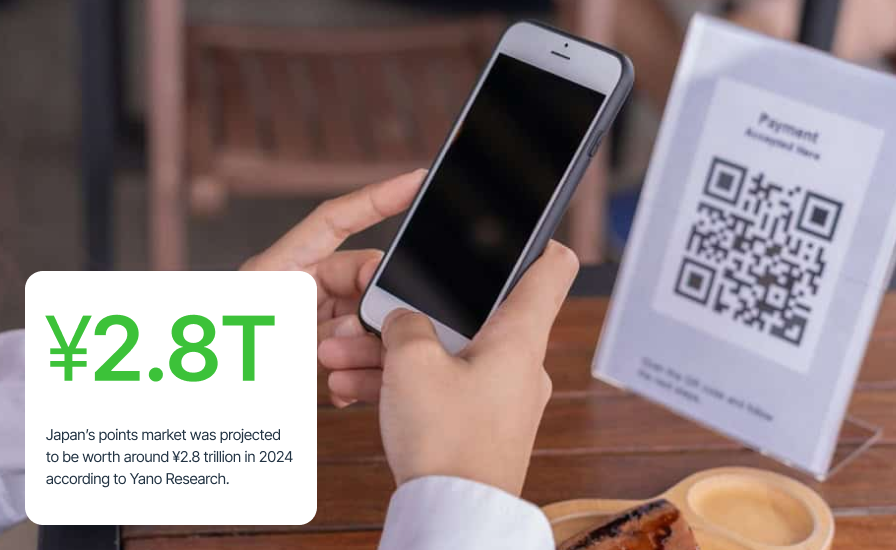
The biggest reason that so many shoppers in Japan use Rakuten Pay is that every purchase is an opportunity to earn or spend Rakuten Points.
While membership reward points in Europe or the US are essentially a bonus tied to one airline, supermarket, or credit card, in Japan, points work more like a second currency and play a huge part in deciding where people shop.
People collect points on their shopping, phone and utility bills, and card spending, and then they can spend them almost anywhere in the same ecosystem. So a customer might earn points from their phone bill and then use those points to buy something from your store. Rakuten covers the value of the points, so you still receive the full order amount.
It’s an incredibly popular payment method. In fact, the Japanese points market was worth ¥2.8 trillion in 2024 and is forecast to reach about ¥3.4 trillion by 2029.
And while PayPay is still Japan’s most-used digital wallet (over 70 million users), Rakuten’s points system has a much wider product offering, so more people use it.
When you dig into the numbers, only 38% of Japanese consumers use PayPay Points, whereas close to 60% for Rakuten Points. Rakuten Pay is also linked to Rakuten Card, Japan’s biggest credit card by spending, with ¥27.7 trillion in shopping transactions in January-June of 2026 alone.
Rakuten also runs regular points campaigns that boost how much customers earn, and people plan their spending around them. During Rakuten Points 10x campaigns, Japanese retailer Sanyo Shokai saw its Rakuten Pay volume more than double.
The other reason Rakuten Pay is so popular, of course, is convenience. Because Rakuten Pay uses the card already saved to the customer’s Rakuten ID, there’s nothing to type in at checkout, which makes a real difference for shoppers buying on their phone.
In short: Japanese shoppers use Rakuten Pay because it keeps their points working for them and makes checkout quicker, and offering it lets them do both in your store.
How does Rakuten Pay work at an online checkout?
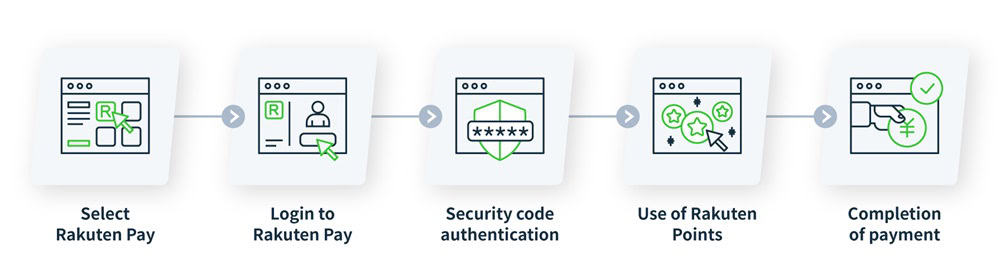
For Japanese customers, paying with Rakuten Pay online involves a few taps in the Rakuten Pay app and no typing card details. Here’s how the payment flow would work for your customers:
- They choose Rakuten Pay as a payment option at your checkout.
- They’re taken to Rakuten’s payment page, where they log in with their Rakuten ID and password.
- They may be asked to enter a security code as an extra check.
- They decide whether to put any of their Rakuten Points towards the order.
- They confirm the payment and are sent back to your store.
Once the payment is confirmed, it shows up in your payment dashboard and you can go ahead and ship the order.
And because customers don’t need to find their card or fill in a form, checkout is quicker and feels familiar. As we know, shoppers in Japan tend to leave checkouts that don’t feel built for them, so giving them familiarity through Rakuten Pay is more than just making your checkout more convenient. It makes it feel local.
It’s also worth knowing that Rakuten Pay payments are processed in yen only, so your prices need to be shown in JPY, ideally with the rest of your checkout in Japanese too.
If you add Rakuten Pay through KOMOJU, payments appear in your KOMOJU dashboard alongside your other Japanese payment methods, and a single payment can be anywhere from ¥100 to ¥9,999,999.
What are the benefits of adding Rakuten Pay to your checkout?
Adding Rakuten Pay to your checkout has extra benefits on top of getting in front of 46 million potential customers. It also makes it easier for Rakuten members to buy from you, builds trust in your brand, localizes your checkout and can boost how much and how often people spend.
Merchants who’ve added Rakuten Pay through KOMOJU have seen these benefits for themselves, and Rakuten regularly publishes case studies showing the impact it’s had for Japanese retailers:
You can win over shoppers who already have a Rakuten ID
Rakuten has more than 100 million member IDs in Japan, so there’s a strong chance your customer already has a Rakuten account when they land on your store. That means the checkout process is quicker and easier for them as they don’t need to create a new account or type in their card details, both of which cause cart abandonment.
And if you’re a new brand or a brand that Japanese shoppers don’t recognize, having familiar payment methods like Rakuten Pay can make a massive difference. In fact, Rakuten’s case studies show that about 60% of Daimaru Matsuzakaya’s Rakuten Pay users were first-time visitors to the site. Another case study shows that fashion brand TOP SECRET saw new customers jump by about 24% after adding Rakuten Pay to their checkout.
You can borrow the trust of a Japanese household name
Trust is an incredibly big deal for Japanese shoppers buying from overseas. In one 2026 survey, 62% said they’d felt more hesitant buying from a foreign site than a Japanese one. On top of that, card fraud losses in Japan reached a record ¥55.5 billion in 2024, so shoppers tend to be cautious when it comes to entering their card details, especially from an overseas brand they’re not hugely familiar with.
By adding Rakuten Pay to your checkout, you take away that apprehension almost entirely. When shoppers see Rakuten Pay as a payment option, they know their payment is going through a company they already use and trust, and that they won’t have to share their card details with your store at all.
Rakuten’s own documents back this up too. In their case studies, they show that electronics retailer XPrice added Rakuten Pay partly because the Rakuten name reassures its customers. And bag brand Artisan&Artist found it won over shoppers who had been uneasy about entering card details on sites they hadn’t used before, which helped cut the number of cash-on-delivery orders it received.
You should see fewer abandoned checkouts
The final step of checkout is where a lot of Japanese sales fall through. And while adding Rakuten Pay isn’t a magic bullet, leaving card-cautious shoppers to find a card and fill in a form on their phone doesn’t help. The more steps there are, the more chances a shopper has to give up before they finish.
By adding Rakuten Pay to your checkout, you make that last step much shorter. Customers just log in with their Rakuten ID and confirm, with no card details to enter. And when shoppers see Rakuten Pay at checkout, they use it. At sportswear brand Goldwin, Rakuten Pay became the second most-used payment method, behind only credit cards.
Accepting Rakuten Pay can lead to bigger and more frequent orders
Because points work like a second currency in Japan, shoppers are always looking for ways to earn more points and for places to spend their points.
By adding Rakuten Pay to your checkout, you can give them both. Customers who pay with a Rakuten Card, their Rakuten Pay balance, or their Rakuten Points earn more points on every order, and they can put the points they’ve saved towards their purchase. So not only do they have a reason to come back, they have an extra reason to add one more thing to their basket.
Artisan&Artist’s — a store that offers Rakuten Pay — saw their customers come back more often and spent ¥770 more per order on average. And at sports retailer Golf Do, Rakuten Pay orders were 23% higher than card orders in one month shortly after it launched.
You’ll lower your fraud and chargeback risk
Chargebacks are a risk wherever you sell, but they can be especially tricky to manage in a market you’re still getting to know.
By adding Rakuten Pay to your checkout, you hand a lot of that risk over to Rakuten. Rakuten checks who’s paying with 3D Secure (an extra identity check from the card issuer) and a security code, and because card details stay with Rakuten, they never touch your systems.
In short: Rakuten Pay helps an overseas brand feel local and trustworthy to Japanese shoppers, and gives them a reason to keep coming back.
Where does Rakuten Pay fit in the ecosystem of Japanese payment methods?
For a lot of international merchants, Rakuten Pay is a second-phase payment method to add after you’ve added local Japanese payment methods like cards, konbini, Paidy and Payeasy.
This is because you need a local entity to offer customers Rakuten Pay, which takes time to set up, and the first-stage methods don’t require one.
In other words, Rakuten Pay is a strong addition to your checkout to drive AOV and conversion rate rather than an essential payment method to offer. And because many Rakuten Pay users pay with the Rakuten Card saved to their account, plenty of them could technically still pay you by card without it.
What Rakuten Pay gives Japanese customers is a reason to choose your store because they can collect points, pay using a name they trust, and checkout quickly and easily.
Here’s how most international merchants think about the Japanese payment method ecosystem:
* Exemptions may apply to some payment methods depending on business model and size of business.
In short: Rakuten Pay probably won’t be the first Japanese payment method you add to your Japanese checkout, but once you’ve set up a local entity, you’ll be able to attract a huge audience of point-conscious shoppers.
[Did you know? Shoppers in Japan expect a lot more choice at checkout than shoppers in Europe or the US, and the average Japanese online store offers 9.5 payment methods, which is more than stores in any other country. Each method tends to serve a slightly different group of shoppers, so a good mix of first-stage methods lets you cover a lot of ground from day one.]
What is a local entity? Do I need one to add Rakuten Pay?
Yes, you need a Japanese entity to accept Rakuten Pay, whether you apply directly through Rakuten or use a payment provider like KOMOJU.
A local entity is a company that’s legally registered in Japan, it has a Japanese corporate registration, a local tax ID, and a local address.
Registering a local entity is a lot more involved than opening a local bank account or signing up for a local service, and the process can take months (not to mention the application is usually in Japanese). Plus, there are ongoing costs associated with a local entity once you’re registered, which is why it’s a good idea to add it once you know there’s demand for your goods in Japan.
(If you want to learn more about registering a local entity, check out our guide.)
Even if you decide to register a local entity straight away so you can add Rakuten Pay, you can add a wide range of Japanese payment methods while you’re completing the registration process. With a payment provider like KOMOJU, you can start selling with:
- konbini payments at FamilyMart, Lawson, Ministop, Daily Yamazaki, and Seicomart
- PayPay, au PAY, and Merpay
- Pay-easy and bank transfer (furikomi)
- Paidy
Each payment method usually only takes a few business days to be approved, so within a week or two you’ll be able to accept the majority of Japanese shoppers’ preferred payment methods.
Plus, PayPay, au PAY, and Merpay — which you can add without a local entity — so you can start rewarding points collectors from day one, even before you add Rakuten Pay.
* Exemptions may apply to some payment methods depending on business model and size of business.
How much does Rakuten Pay cost? How do payouts work?
Like all payment methods, Rakuten Pay charges per transaction that it processes, but that transaction cost depends on whether you sign up with Rakuten directly or go through a payment provider.
On average, Rakuten Pay costs around 4% per transaction for physical goods and around 8% for digital content, with no setup or monthly fees. The fee covers card processing and the points customers earn when they shop with you, so there’s nothing extra to pay for the points side of things.
The exact rate depends on how you sign up:
- Directly with Rakuten: 4.0% for physical goods and from 8.0% for digital content (excluding tax).
- Through a Japanese payment provider like KOMOJU: 4.40% for physical goods and 8.40% for digital downloads.
However, the big difference is in how you get paid as an overseas merchant.
With Rakuten Pay, your customers always pay in yen. If you go to Rakuten directly, payouts have to be sent to a Japanese bank account in yen. Payouts are free to a Rakuten Bank account, or ¥330 per payout to any other Japanese bank. They don’t do international payouts.
With KOMOJU, you can be paid in yen, Korean won, US dollars or euros, straight into your own bank account outside Japan. You can choose to be paid weekly or monthly, with a flat fee of ¥2,500 per international payout.
In short: going direct can work well if you already have a Japanese team and bank account. If you’re selling into Japan from overseas, a provider like KOMOJU means you can manage Rakuten Pay alongside everything else, in your own language and currency.
Can I sign up with Rakuten directly or do I need a payment provider?
You don’t need a payment provider to add Rakuten Pay to your checkout, you can sign up with Rakuten directly.
However, going direct to Rakuten means completing their application and going through Rakuten’s own screening process. The application, setup materials, and support are all in Japanese, so you’ll need someone on your team who’s comfortable working in Japanese.
If you go through a Japanese payment provider like KOMOJU, you can add Rakuten Pay alongside other Japanese payment methods with a single contract and integration. All the applications are in English, you have expert support and you have access to an extensive range of other localized Japanese payments to add to your checkout at the same time.
Does Rakuten Pay work with Shopify and other platforms?
Yes, but not through Shopify Payments. Shopify Payments doesn’t offer Rakuten Pay, so you’ll need to add a payment provider that supports it, like KOMOJU, alongside your existing setup.
That doesn’t mean you have to completely rebuild your checkout, though. KOMOJU connects to Shopify as an additional payment provider, so your cards keep running through Shopify Payments as normal, while Rakuten Pay orders go through KOMOJU.
For your customers, Rakuten Pay simply shows up as one more option at checkout. And because KOMOJU handles your other Japanese payment methods too, you can add konbini, PayPay, and the rest through the same integration.
(It’s worth knowing that Shopify charges 0.2% to 2.0% on payments processed through third-party providers, depending on your plan.)
It works the same way if you use Stripe or Adyen, too. Lots of international merchants selling into Japan keep their existing provider for cards and their other markets, and use KOMOJU just for Japanese transactions.
If you’re on WooCommerce, KOMOJU has its own plugin, and our guide to Japanese payments on WooCommerce walks through the setup. There are also plugins for Wix and Magento, a hosted payment page, and an API if you’ve built your own checkout.
How you can add Rakuten Pay to your checkout with KOMOJU
If you’re selling into Japan from overseas, KOMOJU lets you add Rakuten Pay alongside the rest of your Japanese payment methods with one account and one integration. And because you can start with the methods that don’t need a local entity, you can begin selling straight away and add Rakuten Pay when you’re ready.
Here’s how the process works:
- Sign up for KOMOJU and start with the payment methods that don’t need a local entity, like konbini, PayPay, au PAY, Merpay, Pay-easy, bank transfer, and Paidy.
- Connect KOMOJU to your store using our plugins for Shopify, WooCommerce, Wix, or Magento, our hosted payment page, or our API.
- Once your Japanese entity is registered, apply for Rakuten Pay on the same KOMOJU account.
- Once you’re approved, Rakuten Pay shows up at your checkout alongside your other payment methods, with no new integration needed.
* Exemptions may apply to some payment methods depending on business model and size of business.
What Rakuten Pay costs with KOMOJU
With KOMOJU, Rakuten Pay costs 4.40% per transaction for physical goods and 8.40% for digital downloads, with no setup or monthly fees. Here’s how that compares with signing up with Rakuten directly:
Data accurate as of [publication date]. Sources: KOMOJU, Rakuten.
Your customers pay in yen, but you can choose to be paid in yen, US dollars, or euros, which makes things a lot simpler if your business is based outside Japan. Payouts arrive weekly or monthly, with a flat fee of ¥2,500 per payout to a bank account outside Japan.
You can issue full refunds, partial refunds, and even multiple partial refunds on the same order. However, Rakuten Pay payments through KOMOJU are one-off only, so if you sell subscriptions, you’ll need another payment method for renewals.
Running KOMOJU alongside Stripe or Shopify Payments
You don’t need to replace your existing setup to use KOMOJU. On Shopify, KOMOJU connects as an additional payment provider alongside Shopify Payments, so your cards keep running as normal while Rakuten Pay orders go through KOMOJU. And if you use Stripe, you can keep it for cards and your other markets, and just let KOMOJU handle your Japanese payment methods.
Security and support
When it comes to security, KOMOJU is compliant with PCI DSS Level 1 and holds ISO 27001 and Japan’s Privacy Mark. Across KOMOJU’s payment volume, the chargeback rate is under 0.1%. And if you ever get stuck, KOMOJU’s support team is on hand to help in English and Japanese.
The bottom line
Rakuten Pay is one of the most effective ways to win over Japan’s points-driven shoppers, and it gives an overseas brand the reassurance of a name they already know and trust.
But for most international merchants, it’s a second step rather than a first. You’ll need a local entity to offer it, and it does its best work alongside cards, konbini, and PayPay.
So the most practical route is to start selling in Japan with the payment methods you can offer without a local entity, see how Japanese shoppers respond to your brand, and then add Rakuten Pay to the same KOMOJU account once you’re set up locally.
And you don’t have to replace anything to do it. You can keep Stripe or Shopify Payments for cards and your other markets, and just let KOMOJU handle your Japanese payments. One integration gives you access to 60+ payment methods across Japan, South Korea, China, Southeast Asia, Europe, and Brazil, with no monthly fees and no local entity needed for most of them.
FAQs
Here are some common questions and answers you might have about Rakuten Pay.
No, you don’t need to sell on Rakuten Ichiba to accept Rakuten Pay. It works on your own online store too, and customers just log in with their Rakuten ID at your checkout.
For the most part, no. Rakuten Pay is built for Rakuten members in Japan, and payments are only processed in yen. If you sell to other markets, you can keep your existing card and local payment setup for those customers.
Yes, you need a Japanese entity to accept Rakuten Pay. But with a payment provider like KOMOJU, you can start selling in Japan without one using konbini, PayPay, au PAY, Merpay, Pay-easy, bank transfer, and Paidy, then add Rakuten Pay later on the same account.
* Exemptions may apply to some payment methods depending on business model and size of business.
No, Rakuten Pay payments through KOMOJU are one-off only, so if you sell subscriptions, you’ll need another payment method for renewals.
No, you don’t have to choose between KOMOJU and Stripe. Stripe doesn’t offer Rakuten Pay, but you can keep Stripe for cards and your other markets, and just add Rakuten Pay through KOMOJU on the same checkout.
Yes. Through KOMOJU, a single Rakuten Pay payment has a ¥100 minimum and a ¥9,999,999 maximum.
Sources: KOMOJU documentation: Rakuten Pay fees, currencies, limits and integrations · Rakuten Group: member numbers · Rakuten Payment: online payment rates, points rules and merchant case studies · Rakuten Today: launch date · Statista: points programme usage · ECDB: payment methods per store · PayPay Corporation: registered users and cashless share · JACCS Payment Solutions: 2022 payment method survey · Japan Consumer Credit Association (via Statista): card fraud losses · Shopify: third-party provider fees
We help businesses accept payments online.