We help businesses accept payments online.
There’s a prevailing idea that Japan is a land of contradictions, and even from the outside, it’s not hard to see why.
Even ignoring the continued prevalence of things like the fax machine, Japanese shoppers were paying by tapping their phone against a reader in a convenience store in 2004, roughly a decade before Apple Pay launched in the US.
And yet, twenty years on, with most of the world gone cashless, Japan still holds more cash relative to the size of its economy than almost any developed market, sitting around 20%, compared to 8% in the US.
But the differences don’t stop there.
For most Western countries, checkouts and payment methods are similar, but not the same. While there are regional differences, if a German shopper lands on a US checkout, or an American shopper lands on an Australian one, it’s all familiar.
The card field is where they expect it. There are payment methods they recognize and trust. Even when the checkout offers localized payment methods — for example, 72.3% of German stores offer bank transfer at checkout, a method far less common in the US or UK — the user experience doesn’t shift too much. They can pay with a card, get redirected to their bank or pay-in-installments. It all feels accessible and familiar.
Japan is different. In fact, ECDB puts the average Japanese eCommerce store at 9.5 ways to pay, the highest of any market it tracks. And that’s because Japan has a much more complex and unique payment method landscape than almost any other country in the world.
For example, a shopper here can order something online, walk to their nearest convenience store and pay for that online order in cash. They can check out through a wallet built entirely around loyalty points rather than their bank account. They can put the charge on their phone bill instead of a card at all.
From the outside, it all feels fractured and complex. But every payment method addresses something specific to the way that Japan’s unique payment culture evolved and developed on its own rather than alongside other countries.
And because Japan can feel daunting, this guide covers every method that Japanese customers expect to find, digs into why each one exists, and looks at what it takes to add it to your checkout.
Japan’s payment market at a glance
Japan’s cashless payments reached ¥162.7 trillion in 2025, according to METI’s most recent figures, published in March 2026. That’s up from around ¥111 trillion in 2022.
Broken down, cards are still the backbone of the Japanese payment market, making up ¥134.6 trillion of the ¥162T and 82.7% of Japan’s cashless spending. Digital wallets like PayPay add up to ¥16.6 trillion – or 10.2% of the cashless spending – and more than double what they were in 2022. (METI, 2025 figures)
That ¥162.7 trillion works out at around 58% of Japan’s total consumer spending, up from 42.8% in 2024.
For online spending, things look a little different.
Credit cards account for 55% of Japanese eCommerce transactions, the highest rate of any country Worldpay tracks in its 2026 Global Payments Report. In Japan, cards are the default, but not the whole story, because the other 45% of the payments are made using payment methods that a Western checkout just doesn’t have.
The key thing to note: Japanese shoppers won't substitute one payment method for another
This is the single most useful thing you can understand about the payment culture in Japan: Japanese customers are very particular about which payment methods they use.
Picture a shopper in London or New York who reaches the checkout and can’t find their preferred payment method. Around 80% of the time they’ll shrug, pick something else, and complete the purchase.
Japanese shoppers behave differently. A 2022 survey by JACCS Payment Solutions found that over 60% abandon the cart entirely when their preferred payment method isn’t available. Rather than looking for another way to pay, they tend to give up on the purchase altogether.
That’s why Japanese eCommerce stores carry more payment options than stores anywhere else in the world, typically nine or more, where most Western stores get by with four or five.
On the flip side, however, Japanese consumers are willing to spend up to $455 on a single product, around $77 above the global average of $378.
So it’s not that Japanese customers are conservative spenders so much as they are conservative with where and how they spend their money.
Credit and debit cards in Japan
Cards are the largest single component of cashless spending in Japan and the first thing any store selling here needs. In fact, credit card penetration among Japanese households sits at around 86.8%.
Of course, revolving credit exists in Japan and customers can opt into paying in instalments at the checkout, but carrying a balance is uncommon and carries a cultural weight in Japan that has no real Western equivalent. Debt here is traditionally tied to a sense of shame, and that shapes how people use the cards they own. Most Japanese customers use their credit cards and pay it off in one lump sum a month later.
In fact, Japanese shoppers have a name for paying like this — ikkai barai, or one lump-sum payment — and it’s how most Japanese customers use a credit card.
The practical consequence for merchants is that plenty of shoppers will have a Japanese credit card and still prefer not to use it online, particularly on a foreign store they haven’t bought from before.
The debit and credit cards that matter in Japan
JCB is the one that catches foreign merchants out. Japan’s only home-grown card network was founded in Tokyo in 1961 and has spent six decades embedding itself in the country’s banking and loyalty infrastructure. Many Japanese consumers hold a JCB card as their primary card, often issued through their bank or employer.
However, acceptance isn’t automatic for foreign merchants, it has to be switched on through your payment provider. When it isn’t, a customer who enters a valid JCB card just gets declined, with nothing to explain why. From where they’re sitting, the problem could be their card or your store, and neither gives them a reason to try a second one.
Visa and Mastercard are widely issued and widely accepted in Japan.
American Express is accepted less broadly than Visa or Mastercard but is well established with major retailers, hotels and restaurants.
UnionPay matters mainly for Chinese visitors and residents rather than the domestic market. Acceptance isn’t universal, though it works at most bank ATMs and at 7-Eleven and Lawson machines.
A note on cards issued outside Japan. Japanese-issued cards are the ones your Japanese customers are using, and getting a Japanese card as a foreign resident can be a slow process that depends on visa type, length of stay and income. That’s why services like Wise and Revolut are popular among foreign residents.
Cash in Japan
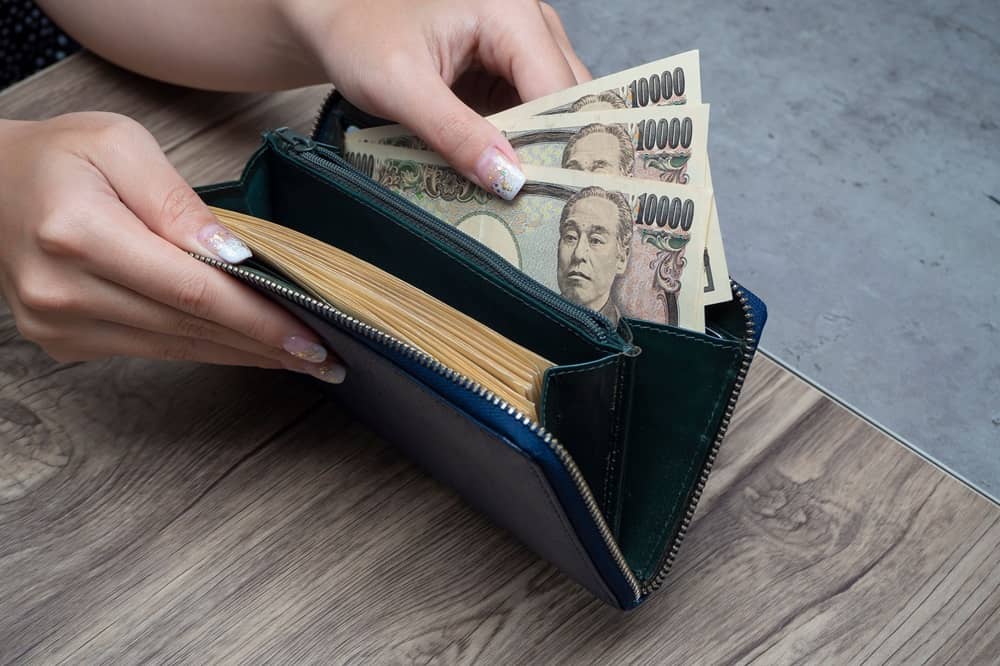
Cash remains a prevalent and widely accepted form of payment in Japan today, despite the global shift toward cashless payments.
In fact, Japan’s cash-to-GDP ratio sits at around 20%, against roughly 8% in the US and under 1% in Sweden. There’s even a word for money kept at home rather than in a bank: tansu yokin, literally savings in the chest of drawers.
And while it’s easy to dismiss this as a Japanese quirk, the cultural reasons for cash’s longevity actually make perfect sense.
- Japan has had decades of near-zero interest rates on banked money, so there has been little reason to move money out of cash, so people haven’t.
- Robbery is rare. Japan records around 1.2 incidents per 100,000 people, against 43.8 in France and 43.2 in Germany. Carrying cash simply isn’t the risk it is elsewhere.
- Cash works when nothing else does. Japan lives with the regular possibility of earthquakes and typhoons, and physical currency keeps functioning when power and networks go down.
- Digital payment breaches have been well publicized. Japan Post Bank withdrew its Visa-backed Mijica prepaid card in January 2021 after hacks led to a ¥53 million compensation payout. Seven & i shut down its 7pay app three months after launch in 2019 following hundreds of unauthorized transactions. Cashless transactions feel risky in Japan.
- Online card fraud keeps setting records. Credit card fraud losses in Japan reached a record ¥55.5 billion, around $370 million, in 2024, with 93% of it coming from card numbers stolen and used at eCommerce sites.
Put those together and you get a shopper who might own a credit card, use it happily in a shop, and still actively prefer not to type it into an unfamiliar website. If they haven’t bought from you before, that’s yours. What cash represents in Japan isn’t only money. It’s the absence of debt, the absence of fraud risk, and something that always works.
Konbini payments: how online businesses can accept cash payments
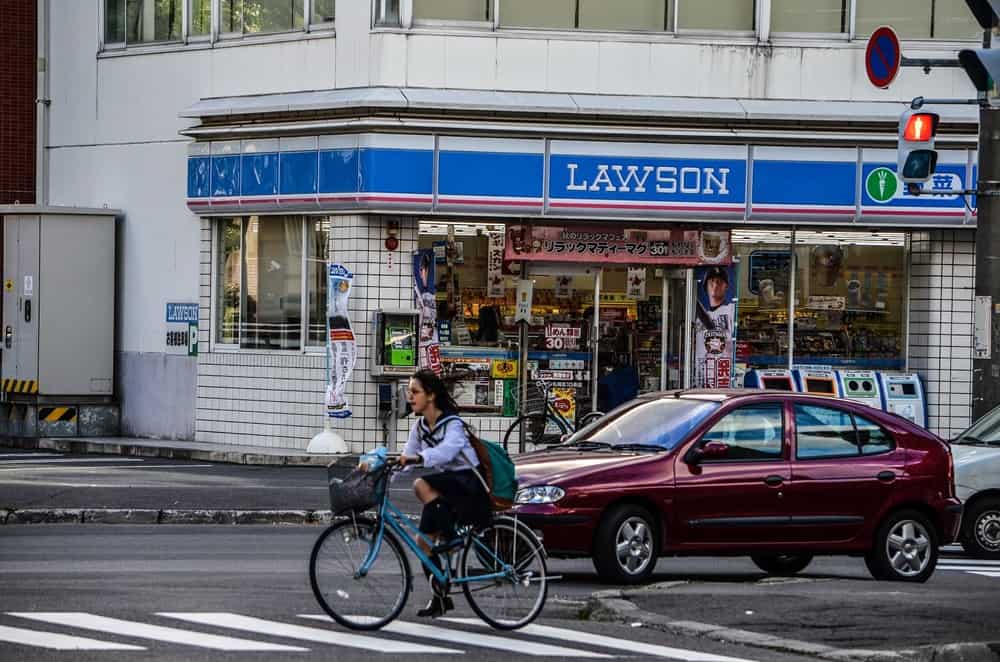
Konbini is the everyday word for a convenience store, and in Japan they do considerably more than sell drinks and snacks. You can make bill payments, withdraw cash, pickup parcels, print things off and pay for online orders. There are more than 56,000 of them, open around the clock, and nearly half of Japanese consumers visit one at least once a week.
Konbini payments use that network to allow customers to pay cash for their online shopping. The customer orders on your site, chooses konbini at checkout, and receives a payment code by email. They walk to any participating store, enter the code at an in-store kiosk, take the printed voucher to the register, and pay in cash. Confirmation reaches you within about an hour, and only then does the order ship.
It’s popular because it lets Japanese customers pay for online purchases without entering their card details into a website. It isn’t a fallback for people who don’t have cards, it’s a popular payment method for people who would rather not expose them to a store they don’t know yet. In fact, more than 20% of Japanese online shoppers regularly use konbini to make a purchase.
How konbini works for online stores:
Konbini payments are completely normal in Japan, so Japanese payment service providers – just like KOMOJU – help stores accept konbini at their checkout every day. Here’s how it works:
- The customer picks konbini at checkout, chooses their preferred chain, and gets a payment code by email, with instructions in Japanese.
- The order sits as unpaid. Nothing ships yet, because nothing’s been paid yet.
- The customer pays in cash at the store. Most konbini are open 24 hours, so this fits around whatever else they’re doing that day.
- Confirmation comes through automatically, usually within the hour, and that’s your signal to ship.
- If they don’t pay in time, the order simply expires. You set how long you’re willing to wait — a few days by default, extendable up to 59 — and an unpaid order costs you nothing.
The standard payment cap is ¥300,000 per transaction, and larger orders can usually be split across more than one payment. There’s a ¥110-¥5,500 fee charged to the customer or the shop, which is standard across the industry and expected by Japanese shoppers.
Our full guide to konbini payments covers the flow in more detail.
Bank transfer and Pay-easy: what Japanese shoppers use for big purchases
Bank transfer, or furikomi, is woven into ordinary Japanese life. Rent and utility bills are commonly paid by automatic withdrawal or manual transfer, and virtually every adult is set up to use it. Around 98% of the population holds a bank account.
Online, bank transfer payments run through Pay-easy, which connects directly to Japan’s major banks and ATM networks. The customer receives payment details at checkout and completes the transfer through online banking or at an ATM, with no card details entered anywhere.
It’s popular because it removes card exposure completely, which matters to Japanese customers when they’re spending larger sums of money. In other words, card anxiety in Japan increases with AOV.
A shopper who will happily put ¥4,000 on a card at an unfamiliar overseas store often will not do the same with ¥40,000. Bank transfer is what makes an expensive first order feel safe enough to complete, which is why it shows up disproportionately in electronics, luxury goods and high-value first purchases.
If your Japanese average order value is coming in below your global average, a missing bank transfer option is one of the likelier explanations. It’s a hard one to spot in your data too, because you don’t lose customers outright, you lose larger orders.
Digital wallets and mobile payments: the heart of Japan's points economy
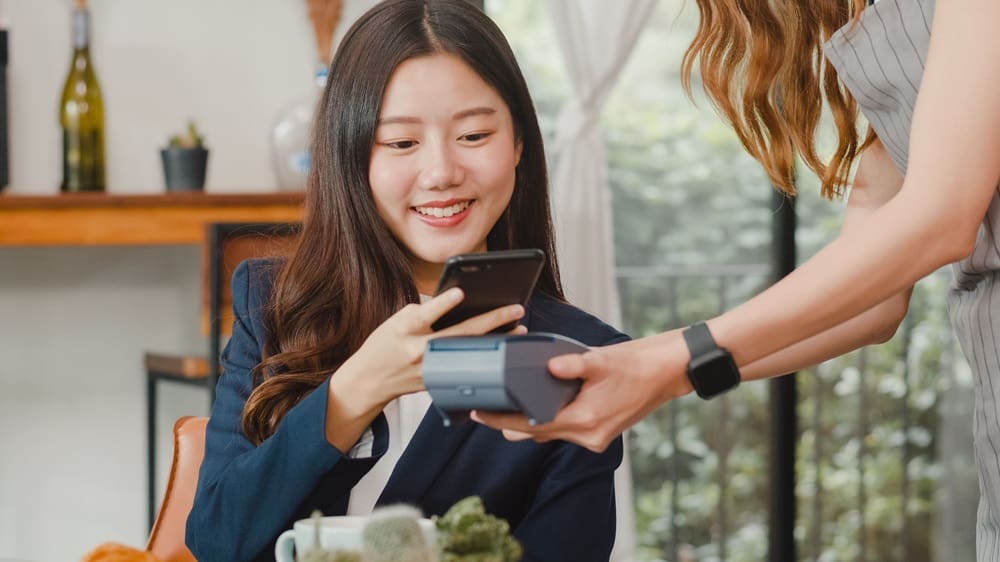
QR code payments accounted for ¥16.6 trillion of Japanese cashless spending in 2025, and mobile payment apps are the fastest-growing category in the market.
(QR Code is a registered trademark of DENSO WAVE INCORPORATED in Japan and in other countries.)
Understanding why QR code payments are so important involves understanding two things about your Japanese customers. The first is debt. A digital wallet in Japan is loaded with money and spent from that balance, which gives people the convenience of paying digitally without anything that resembles borrowing. That’s not specific to digital wallets, but it’s a part of it.
The other part is loyalty points.
In Japan, points — like Rakuten Points, d Points, PayPay points — aren’t just a reward for spending, like they are in the West. They’re closer to a second currency, and more than 80% of Japanese people between 15 and 79 actively look for ways to earn points on everyday purchases, whatever they’re buying or wherever they’re spending. There’s a name for it: poi-katsu, point activity, and it’s entirely mainstream.
An update for merchants in 2026: If you’ve read older guides that mention LINE Pay, which for years appeared near the top of every Japanese wallet ranking, it has now terminated its Japan service and been integrated into PayPay.
PayPay
PayPay is Japan’s dominant QR wallet, and the one most merchants add first, with over 70 million registered users as of July 2025. That’s more than one in two people in the country, and it rose to 72 million users in December 2025. It processed 7.46 billion transactions in 2024, which made up roughly 20% of all Japanese cashless transactions that year, credit cards included.
It’s the simplest version of the popular no-debt, no-card-details proposition, and it runs frequent cashback and points campaigns that genuinely make a difference to where people shop. It also reaches two demographics that can’t be reached with credit cards: younger shoppers who can’t yet apply for a credit card, and older shoppers wary of entering card details online but who collect points.
Rakuten Pay
Having Rakuten Pay on your checkout is less about accepting it as a payment option and more about giving customers the option to collect their points. Rakuten Points are used by close to 60% of Japanese consumers across more than 70 services, from shopping to travel to banking to mobile.
For gaining traction in Japan, that’s huge. A Rakuten-loyal customer can arrive at your checkout with accumulated points and a habit of shopping wherever those points work and be more willing to check out because they will gain more points. Put another way, it’s an easy way to join an economy that runs alongside the Japanese yen for tens of millions of people. You don’t need to sell on Rakuten Ichiba to participate.
au PAY
au PAY is KDDI’s mobile wallet, built around Ponta points rather than Rakuten’s, and funded in a way no other wallet on this list works: because KDDI is also Japan’s second-largest mobile carrier, a customer can top up their au PAY balance straight from their au, UQ or povo phone bill, with no bank account or card required at any point. It’s grown to approximately 31.6 million users, and every purchase earns Ponta points redeemable well beyond KDDI’s own services.
d Barai
d Payment belongs to NTT Docomo, Japan’s largest mobile carrier, and works the same way, with a balance charged to the customer’s monthly phone bill. It has 60 million registered users and is accepted at more than 5.2 million locations nationwide. Points accumulate under the d Points scheme across ordinary purchases and the phone bill itself, and Docomo has spent the last few years building that program into something closer to a financial ecosystem than a mobile plan.
Merpay
Merpay is attached to Mercari, Japan’s dominant secondhand marketplace (like Depop or Vinted), with more than 22 million monthly active users. It’s a unique Japanese payment method because it’s loaded up with a seller’s proceeds from something they’ve just sold on Mercari and is spendable immediately with no bank transfer step in between. More than 15 million people use the wallet, and it’s accepted at 1.7 million merchants in Japan.
Apple Pay, Google Pay and travel cards
Japanese shoppers can load Suica, PASMO and ICOCA travel cards into Apple Wallet, and those cards work far beyond the station gate, at konbini, restaurants, shops and vending machines. These are among the most established contactless payment options in the country, running on the FeliCa infrastructure from the garakei era, now wrapped in a modern phone.
Carrier billing: reaching customers who don't hold a card
In most Western markets a mobile carrier lets you send messages, use data and make calls. In Japan, the three major carriers have spent decades turning themselves into something closer to banking apps than mobile networks.
Carrier billing charges a purchase to the customer’s monthly phone bill, or draws it from a prepaid balance. That means no card, no bank account and no separate signup process. It’s the most frictionless route from intent to purchase in Japan, especially for younger customers who don’t qualify for a credit card yet. It’s strongest in digital goods, games, in-app content and subscriptions.
- NTT Docomo is the largest, with approximately 91.9 million subscribers, its own d Point programme, and a recent $5.1 billion move to acquire SBI Sumishin Net Bank — folding loans, mortgages and savings into the same ecosystem a customer already pays their phone bill through.
- KDDI (au) reached approximately 71.5 million subscribers, and every one of them can fund an au PAY purchase straight from the phone bill — no bank account or card required at any point in the chain.
- SoftBank is Japan’s third-largest carrier, with approximately 56.4 million subscribers on its own nationwide network. It runs the same phone-bill mechanism as Docomo and au — SoftBank Matomete Shiharai — authenticated through a customer’s My SoftBank login rather than any payment details at all.
- Rakuten Mobile is the newest and smallest of the four, with around 9.3 million subscribers, but it doesn’t need scale to compete because it inherits Rakuten’s existing points economy, already used by close to 60% of Japanese consumers across more than 70 services, from the moment a customer signs up.
Paidy and BNPL: offering Japanese customers instalment plans without the cultural baggage of credit
Buy now, pay later works against a different backdrop in Japan than it does in the West. Western BNPL competes with credit cards already built around revolving balances. Here, the default is paying in full the following month, and switching to installments typically means interest around 15–18%, plus the cultural weight of being seen to borrow.
Services like Paidy and Atone sidestep that. They let Japanese customers buy something today and add it to a running tab so that everything purchased that month lands on one consolidated bill, due in full the following month, by bank transfer, konbini or account transfer. There’s no interest if it’s settled that way. (And just like credit cards, the tradition of ikkai barai applies here too.)
Of course, installment plans exist on top of that, so customers can spread payments across 3, 6 or up to 36 months, but they’re the option, not the default.
Prepaid wallets: the default for gaming and digital content
Services like BitCash and WebMoney let customers load a balance and spend it online without linking an account or using a card. WebMoney holds the largest share of the two, and both are built into the platforms like DMM, DLsite, Steam and PlayStation Store.
As such, it’s the natural fit for younger buyers, and for anyone who wants a hard ceiling on what a purchase can cost them. Among Japanese gamers specifically, over 40% actively avoid credit cards altogether, leaning on prepaid, carrier billing and other card-free methods instead.
If you sell games, in-game currency, manga or streaming top-ups, prepaid wallets give you access to close to half your addressable audience.
What this means if you're selling into Japan
Although Japan’s payment method market can seem complex, every payment method here is addressing and adapting to the same cultural attitudes toward money and spending in a different way.
Konbini lets someone pay in cash without a card ever touching your site. PayPay lets them pay digitally without taking on debt. Pay-easy moves money without exposing a card number. Paidy settles the bill next month without needing one at all. Carrier billing works without a bank account.
The final complication comes from something called a local entity.
In a lot of markets, you can sign up with a payment provider and start taking local payments the same day. Japan often works a little differently.
In Japan, accepting most of the popular payment methods is dependent on having what’s called a local entity: a company legally registered in Japan, with a corporate registration, a local tax ID and usually a local address.
Getting set up with one is months of paperwork (in Japanese) and an ongoing expense, making it the kind of thing most merchants do once they have a real foothold in Japan, not when they’re testing the market.
For example, with Stripe, you’ll need a local entity to offer anything beyond JCB and yen payments in Japan. Konbini payments, PayPay and bank transfer all require a Japan-based Stripe account, which means a Japanese company or sole-proprietor registration before you can add them to your checkout.
However, with KOMOJU, you can add a lot of popular payment methods to your Japanese checkout without a local entity, including five konbini chains (FamilyMart, Lawson, MiniStop, Daily Yamazaki and Seicomart), bank transfer, Pay-easy and Paidy.
(Did you know that research across 50+ global payment methods found that just adding konbini to your Japanese checkout produces a 27% lift in conversion for Japanese customers?)
And if you do decide to set up a local entity down the line, you can add 7-Eleven — the biggest konbini chain in the country — process cards directly (Visa, Mastercard, JCB, Amex), and reach further into the market with d-barai, carrier billing through Docomo, SoftBank and au, and prepaid wallets like BitCash and WebMoney.
In other words, KOMOJU lets you start with a checkout that already covers most of Japan without a local entity and then upgrade and optimize once you’ve got traction and a local entity.
Frequently asked questions about Japanese payment options
What is the most used payment method in Japan?
Credit cards, by value — they make up 82.7% of Japan’s overall cashless spending. Online, the picture is broader: cards still lead, but konbini, digital wallets like PayPay, bank transfer via Pay-easy and carrier billing each hold a meaningful share, which is why a card-only checkout leaves money on the table.
Is Japan a cash or card society?
Both, and increasingly card. METI put cashless payments at 58.0% of consumer spending in 2025, though that figure uses a new domestic indicator introduced in December 2025 — on the previous basis it’s closer to 46.3%. Cash remains common at family-run restaurants and smaller local businesses, and is a deliberate preference for many shoppers online too.
What cashless payments are available in Japan?
More than most markets. The main cashless payment methods are cards, digital wallets like PayPay and Rakuten Pay, electronic money such as Suica, and the card-free routes — konbini, bank transfer via Pay-easy, carrier billing and BNPL through Paidy. Nearly all of them work online, which is why Japan’s shift toward a cashless society hasn’t simplified checkout the way it has elsewhere: more electronic payments has meant more cashless payment options to support, not fewer.
Does Japan use Apple Pay?
Yes, and it works a little differently here. Japanese iPhones carry Sony’s FeliCa chip, so Apple Pay can hold Suica, PASMO and ICOCA travel cards alongside ordinary credit cards — and those travel cards are accepted well beyond the station gate. For a merchant, Apple Pay isn’t a separate method to negotiate; it’s a layer over whichever card sits underneath, so what matters is whether you accept the networks your customers have loaded into it — JCB included.
Can I accept Suica, PASMO or other IC cards on my online store?
Not on a standard web checkout. Japan’s travel IC cards are contactless instruments built for a physical reader, which is why METI counts them as electronic money rather than an eCommerce payment method. The nearest online equivalent is Apple Pay or Google Pay on a mobile checkout, where the customer is really paying with the card held in the same wallet.
Can foreigners get a credit card in Japan?
Yes, though approval depends on visa type, length of stay and income, and it can be slow. Foreign residents often use Wise or Revolut in the meantime because both offer debit cards with no credit screening, which is the real draw for someone who hasn’t built Japanese credit history yet. For merchants, the relevant point is that some of your Japan traffic will be foreign residents paying on non-Japanese cards, which can carry higher cross-border decline rates than domestic ones.
What is konbini payment and how does it work?
The customer selects konbini at checkout and gets a payment code by email. They take it to any participating convenience store, pay in cash at the register, and confirmation reaches the merchant within about an hour. The order ships once payment is confirmed, so there’s nothing to charge back. There’s a ¥110-¥5,500 fee charged to the customer or the shop, which is standard across the industry and expected by Japanese shoppers.
Do I need a Japanese company to accept Japanese payment methods?
Not for most of them. Through KOMOJU you can launch with five konbini chains — FamilyMart, Lawson, MiniStop, Daily Yamazaki and Seicomart — plus bank transfer, Pay-easy and Paidy, all without a local entity. Other Japanese payment methods require one.
Is LINE Pay still available in Japan?
No. LINE Pay’s Japan service ended on 30 April 2025 and was folded into PayPay, with users able to transfer their balances across. Any guide still listing it among Japan’s leading wallets is out of date.
Why do Japanese shoppers abandon carts more often on foreign sites?
Because they’re less willing than Western shoppers to substitute one payment method for another and over 60% will abandon a purchase entirely if their preferred method isn’t available, rather than picking something else. On a store they haven’t used before, that’s compounded by wariness about entering card details at all, which is well-founded given card fraud losses hit a record ¥55.5 billion in 2024.
We help businesses accept payments online.