We help businesses accept payments online.
Setting up your eCommerce store to sell in Japan looks straightforward. With most eCommerce platforms – WooCommerce, Shopify, Wix, etc… — you can add pricing in yen and take the major credit cards, Japan’s JCB included, without much effort.
On paper, all it takes is a few clicks and your checkout is Japan-ready.
However, that is very rarely the reality for most merchants selling into the Japanese market for the first time.
Even if your traffic from Japan is healthy – your ads get clicks, your product pages get views and your products get added to carts – most first-time merchants often see Japanese shoppers drop off and abandon their carts despite doing everything “right”.
On top of that, the usual Western playbook — CRO tweaks, abandoned-cart emails, discount codes — don’t usually do much to turn things around because it’s not pricing or UX that have actually caused Japanese customers to abandon their carts.
(In fact, discounting can actively work against you in Japan: shoppers here often read price as a signal of quality and trust, so an aggressive markdown from an unfamiliar overseas store can raise doubt rather than tempt a sale.)
Now, of course, the usual Western conversion-killing culprits — surprise costs, a clunky checkout, forced account creation — are all relevant in Japan too, but they’re not the deal-breakers.
The biggest conversion killer in Japan is the moment that a customer goes to choose their preferred payment method and doesn’t see the one they meant to use.
In fact, a 2022 survey by JACCS Payment Solutions found that over 60% of Japanese shoppers abandon a purchase entirely when their preferred payment method isn’t there.
In the West, most shoppers in that position — around 80% — simply pick another option and carry on. Japanese shoppers don’t.
The tricky thing is that none of this shows up as an error message. From the outside, nothing looks broken. But a checkout that isn’t built for Japanese shoppers will give itself away in five specific places in your data. So here’s a rundown on how to spot whether your checkout is optimized for Japanese shoppers or not.
Sign 1: Your cart abandonment in Japan is far higher than your other international markets
There’s a common misconception among international merchants that Japan’s abandoned cart rates are incredibly high. However, when you dig into it, Japan’s average cart abandonment rate is actually lower than the global average.
Japan’s average abandoned cart rate sits around 62.9%, rising to around 70% in categories like apparel. That means, even at the top-end, Japan’s abandoned cart rate is on par with the 70.19% global average abandoned cart rate.
So if you’re selling into Japan and your abandonment is noticeably higher than other markets, then the market isn’t the reason. Japanese shoppers are not unusually prone to abandoning their carts, which means there’s something else at play stopping them from checking out.
Because while Japanese shoppers abandon carts at a perfectly normal rate if stores are built for them, they walk away from foreign checkouts at a much higher rate.
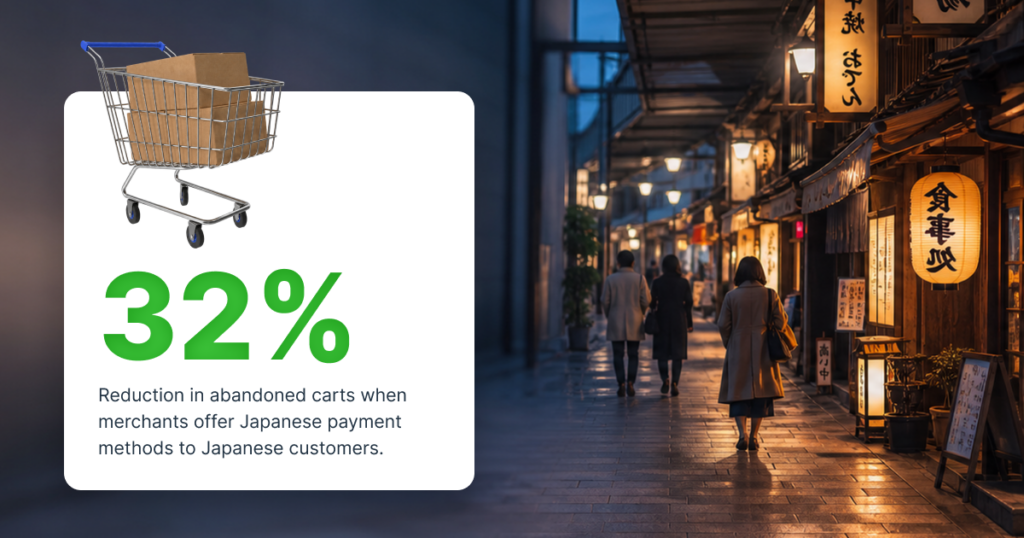
In fact, PYMNTS, surveying 500 merchant leaders across the US, UK and Canada, found that cart abandonment ran 32% higher for merchants who didn’t offer localized payment options for APAC shoppers compared to those who did.
How to check:
Segment your abandonment by country and put Japan next to your two or three biggest markets.
Because you’re selling cross-border, you’d expect Japan to run a little higher than at home due to things like international shipping, customs and unfamiliarity that all add friction. That’s all completely separate from payment methods and out of your control.
So a small gap is normal. What isn’t normal is a large gap.
If your Japanese checkout is sitting ten, fifteen or twenty percentage points worse than your other markets, that’s a sign that there are reasons bigger than cross-border friction at play.
Sign 2: Shoppers exit at the payment step, not the cost or delivery step
In most Western markets, the most common cause for abandoned carts is surprise fees or additional costs.
In fact, Baymard Institute’s research puts unexpected shipping, tax and fees as the single biggest cause of cart abandonment, cited by roughly two in five customers who leave things in their carts. That’s why so much Western conversion advice is built around transparency and risk reduction.
In Japan, however, shoppers tend to get through shipping and costs without much trouble, then leave the moment payment options appear.
That’s because payment choice in Japan isn’t really a preference in the way Western shoppers experience it. Japanese ecommerce stores offer more payment methods than stores in most other countries, typically nine or more where most Western stores offer four or five.
On top of that, each payment exists for a specific cultural reason that goes beyond just convenience. Unlike a Western customer, the payment methods that each Japanese customer uses is personal and grounded in their ideas about cash, debt and spending.
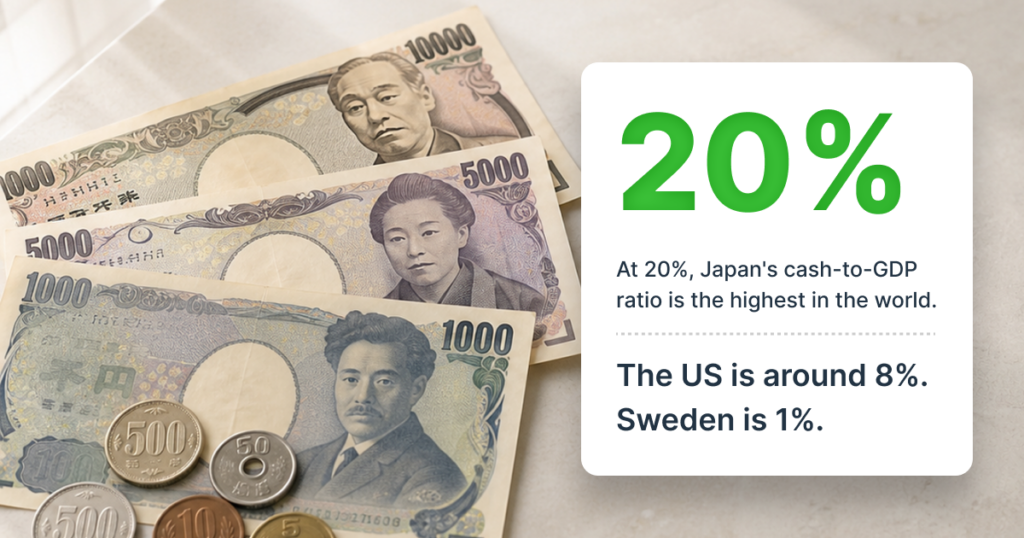
Take konbini payments for example. Japan’s cash-to-GDP ratio sits around 20% — compared to roughly 8% in the US and under 1% in Sweden — and there’s even a word, tansu yokin, for cash kept at home rather than in a bank: literally “savings in the chest of drawers.”
In fact, a large share of the cash in Japan isn’t circulating at all, it’s sitting in people’s homes. Konbini payments are built to take Japanese culture’s inherent trust in cash and make it work for online shopping.
Similarly, PayPay payments cater to customers who would ordinarily use a credit card but don’t like the association with debt.
Interestingly, while Japanese credit card ownership is high, revolving debt carries real cultural weight and is rare in practice. Credit cards in Japan are used very carefully and cleared month-to-month, they’re not treated as flexible debt like in the West. (This is called ikkai barai, which is Japanese for lump sum.)
That’s why PayPay lets people spend from a balance just like a credit card, but they’ve already pre-loaded their balance with money so there’s no card exposure and nothing that resembles borrowing or revolving debt. And that’s a large part of why it has over 70 million registered users.
And so on and so on.
Every payment in Japan – from bank transfers to loyalty points – has a large subsection of Japanese users that would rather go without the product than choose a different way to checkout.
So if you’re seeing drop off after they’ve selected delivery, it’s almost certainly not a question of logistics but a question of whether you’re offering them the right payment methods to pay with.
How to check:
Look at all the Japanese traffic data for your checkout funnel and map the exit rate at each step. Look at when they add to cart, when they see shipping/costs and when they choose a payment method.
If you’re seeing a drop-off when they see payment methods, that’s a localization issue, not a UX challenge.
Sign 3: Your card decline rate and payment failures in Japan are unusually high
This is one of those localization nuances that catches out a lot of first-time merchants because it looks like a technical issue rather than a localization issue.
If you look at your payment failures and transaction failures for Japanese customers and notice that Japanese cards are getting declined at a noticeably higher rate than cards in your other markets, the most likely explanation is due to the nuances around JCB card acceptance.
JCB is Japan’s only home-grown credit card network, founded in Tokyo in 1961 and woven into the country’s banking and loyalty infrastructure over the last six decades.
Plenty of Japanese consumers carry one as their main card, often issued through their bank or employer. In fact, nearly one in five cards in Japan is JCB.
However, the thing that catches merchants out is that whether you can accept JCB payments depends on your payment provider, your account’s country and sometimes an eligibility check.
For example, a Stripe account in the UK, US or EEA can accept JCB payments from anywhere in the world more or less by default.
For a store using Shopify Payments, you can accept it, but only if your account is eligible.
With KOMOJU, you can accept JCB payments, but you need a local entity.
And for merchants using other gateways, it can mean anything from a separate activation to not being offered at all.
However, here’s where merchants encounter difficulties. .
Because JCB is a credit card – with 16 digits, expiry date and CCV – and most card fields for online stores will let customers enter and submit any valid card number they type in. So a JCB card user can enter their card details perfectly, hit submit and then see a decline with no explanation as to why they couldn’t place their order.
However, this is a bit of a silver lining, because the customer did everything right and had every intention of checking out. So once it’s fixed, it’s low-hanging CRO fruit.
What to check: decline rates for Japanese cards against your global baseline and whether JCB is actually live on your account. (Your provider advertising JCB and it being live on your account are sometimes different things.)
Sign 4: Your Japanese average order value is below your global average
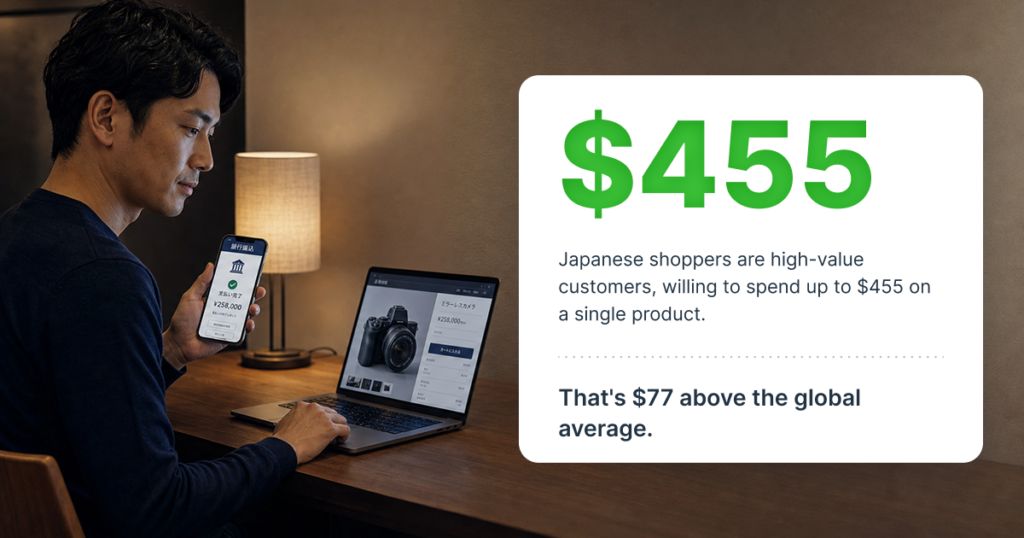
Most merchants outside of Japan don’t realise this, but Japanese shoppers are high-value customers. PCMI’s research finds they’re willing to spend up to $455 on a single product, around $77 more than the global average.
That means that if your Japanese AOV is coming in lower than your global AOV, that’s a wrinkle that’s worth investigating.
And the usual culprit is a checkout that is silently filtering out high-value orders because it lacks the trust signals that Japanese customers need to place high-value orders.
In the West, those trust signals look like reviews and returns policies. In Japan, those things matter too. But the biggest trust signals are the payment options you offer.
You see, card anxiety in Japan scales with order value. In 2024, credit card fraud losses in Japan hit a record ¥55.5 billion, around $370 million, and 93% of them came from card numbers stolen and used at ecommerce sites.
That means, for those larger purchases, Japanese shoppers prefer to reach for bank transfer or Pay-easy, which allows them to move money directly from their account to the merchant, no card details entered anywhere.
But most international merchants don’t realise this – partially because accepting bank transfers is quite an alien and novel approach for most Western businesses – but if you’re selling in Japan and you don’t offer it, you’re risking losing out on big orders.
How to check:
The obvious place to start is to compare your Japanese AOV against your global AOV. If it’s much lower, that’s a sign that something is amiss. Then, if you track it, see if your Japanese abandoned carts AOV is higher than your confirmed order AOV.
If that’s the case, you’re likely looking at revenue lost because Japanese shoppers prefer to use bank transfers for larger purchases.
Sign 5: Your Japanese customers buy once and don't come back

Japan should be one of your strongest repeat-purchase markets. Japanese consumers research carefully before a first purchase, and once a store earns their trust they tend to be loyal and high-value over a long period. That’s a large part of why the Japanese market is worth the effort.
That means that a healthy first-purchase rate paired with a weak repeat purchase rate is a signal that’s well worth paying attention to.
And if you’re seeing a drop off in customer loyalty and repeat purchases, points might be a big part of why.
In Japan, loyalty points function less like a reward for spending (like they do in the West) and more like a parallel currency.
Rakuten Points alone are used by close to 60% of consumers across more than 70 services, and a large majority of Japanese shoppers factor in what they’ll earn before deciding where to buy. A shopper choosing between your store and a competitor’s may well decide on where the points land rather than on the product.
Wallets like Rakuten Pay, au PAY and d Payment plug into those ecosystems directly.
Without them, every Japanese purchase from your store is a transaction that the customer can’t collect points on, which gives them no particular reason to choose you again next time.
What to check: repeat purchase rate for Japanese customers against your other markets, and whether your Japanese customers are earning anything they actually collect.
If you’re already offering points-linked wallets and repeat purchases are still down, it’s worth taking a look at what happens after the sale.
Japanese shoppers expect clear, precise communication once they’ve ordered. That means accurate delivery windows, a proper returns and exchange policy, confirmation emails that are precise and detail-oriented.
None of those things will necessarily stop a first purchase, but in a market where trust is earned in the details, it’s often enough to introduce doubt around placing a second one.
What all five signs have in common
You’ve probably noticed that in every one of the five signs, the shopper had already decided to buy your product and check out.
The abandonment gap, the payment-step exits, the silent declines, the capped order values, the customers who never return… every single one is a purchase that would have made it all the way to your Confirmed Orders tab (and your bottom line) if something hadn’t stopped them.
But most merchants don’t think about payment methods as a CRO blocker.
In fact, in PYMNTS’ survey of merchants selling to APAC customers, 60% of them blamed abandoned carts on shipping costs, but the same study found it was actually adding localized payments that moved the needle, cutting abandonment by 32%.
In other words, the Western playbook for reducing abandoned carts doesn’t apply in Japan. You need to adapt your checkout – and your CRO tactics – to the nuances and intricacies of Japan’s payment culture.
And that’s exactly what KOMOJU is here for.
Most merchants struggle to localize their checkouts because each of Japan’s payment methods each belong to a different company, with its own merchant agreement, its own onboarding (most of it conducted in Japanese) and several of them won’t contract with a foreign business at all unless it’s registered in Japan.
For most merchants, incorporating in Japan before you’ve proven the market is a non-starter.
But as a registered payment service provider in Japan, KOMOJU lets you add konbini payments across five major chains, PayPay, au PAY, Merpay, bank transfer, Pay-easy and Paidy to your existing checkout with no Japanese entity required.
That means you can accept cash, wallets and bank transfer, the methods behind most of the ways Japan actually pays.
Then, once Japan has proven itself as a market, you can register locally and extend to the full range, including 7-Eleven, JCB and the rest.
And because it all sits alongside your current payment provider rather than replacing it, everything else can stay running exactly as it is.
The bottom line
Whether you’re seeing an abnormal abandonment gap or drop-off at payment or elevated declines or any of the other symptoms we listed, the underlying cause is still the same: you’ve got a checkout that’s built for your home market (or a Western audience) rather than a checkout that’s built for shoppers who decide whether to checkout based on a complete different culture around payments.
The good news? You’re not alone in hitting this wall. Almost every merchant who launches in Japan runs into some variation of this localization issue.
Take Steam, for example. When one of the world’s largest PC gaming platforms first arrived in Japan, its checkout was built entirely for a Western audience: an English-only interface, prices in USD, and none of the payment methods Japanese users actually wanted to use. They had the data to show that Japanese gamers wanted to spend on PC games, the problem was Steam had a checkout that gave them no comfortable way to do it.
The fix wasn’t fancy CRO tricks. Instead, Steam added Japanese-language support, switched to yen pricing, and brought in konbini payments alongside other local methods through KOMOJU, so that Japanese customers could pay for games like any other local purchase. The year after the localized checkout went live, Japan was the fastest growing region for Steam users anywhere in the world.
That’s the value of localizing your checkout for how Japanese customers like to shop. Japan is a lucrative market – the 3rd largest ecommerce market in the world – you just need to adapt your store (and checkout) to its nuances and complexities to start tapping into it.
Frequently asked questions
What is the average cart abandonment rate in Japan?
Around 62.9% on average, rising to roughly 70% in categories like apparel, according to e-Agency’s annual survey. That’s about seven points better than the global average of 70.19% measured by Baymard Institute, so Japanese ecommerce outperforms the global benchmark. That figure reflects domestic stores built around Japanese payment habits, though. Merchants selling into the region without localized payments see abandonment run around 32% higher than those who localize.
How does an abandoned online shopping cart work?
A shopper adds items to their online shopping cart, begins the checkout process, and leaves before completing payment. The order is never created, so nothing is charged and the items are released. Most ecommerce platforms record it as an abandoned cart and can trigger a recovery email. In Japan specifically, a large share of these exits happen at the payment step rather than earlier.
How do you fix cart abandonment in Japan?
Start by finding where shoppers exit. If the drop is concentrated at payment selection, the fix is offering the methods Japanese shoppers expect: konbini, PayPay, Rakuten Pay, bank transfer via Pay-easy, carrier billing, and JCB explicitly enabled on your cards. Recovery emails and checkout tidying help, but they can’t recover a customer who had no acceptable way to pay.
How do you avoid cart abandonment before it happens?
Show full prices in yen with no late surprises, make the mobile experience fast, offer guest checkout, publish clear delivery and return or exchange policies, and give shoppers their preferred payment methods at the point of payment. In Japan the last one carries the most weight, because limited payment options are the single biggest cause of abandonment.
Does adding local payment options actually improve conversion rates?
Yes. One independent study across 50+ payment methods found konbini alone lifted conversion by 27% for Japanese customers. Part of that comes down to how konbini works: once a shopper generates a payment voucher, they’ve committed to a specific store trip rather than a single tap, so fewer drop out along the way. And because payment is confirmed in cash before anything ships, fraud and chargebacks are close to a non-issue.
Sources: KOMOJU internal research · e-Agency CART RECOVERY annual survey — Japanese cart abandonment rates · Baymard Institute — global average cart abandonment rate · PYMNTS — localized payments and APAC cart abandonment · JACCS Payment Solutions — 2022 payment method survey · Statista — online payment methods of digital buyers; credit card fraud losses (Japan Consumer Credit Association data); cross-border ecommerce and consumer hesitancy · PCMI — Japanese ecommerce spend benchmarks · PayPay Corporation — registered user figures.
We help businesses accept payments online.